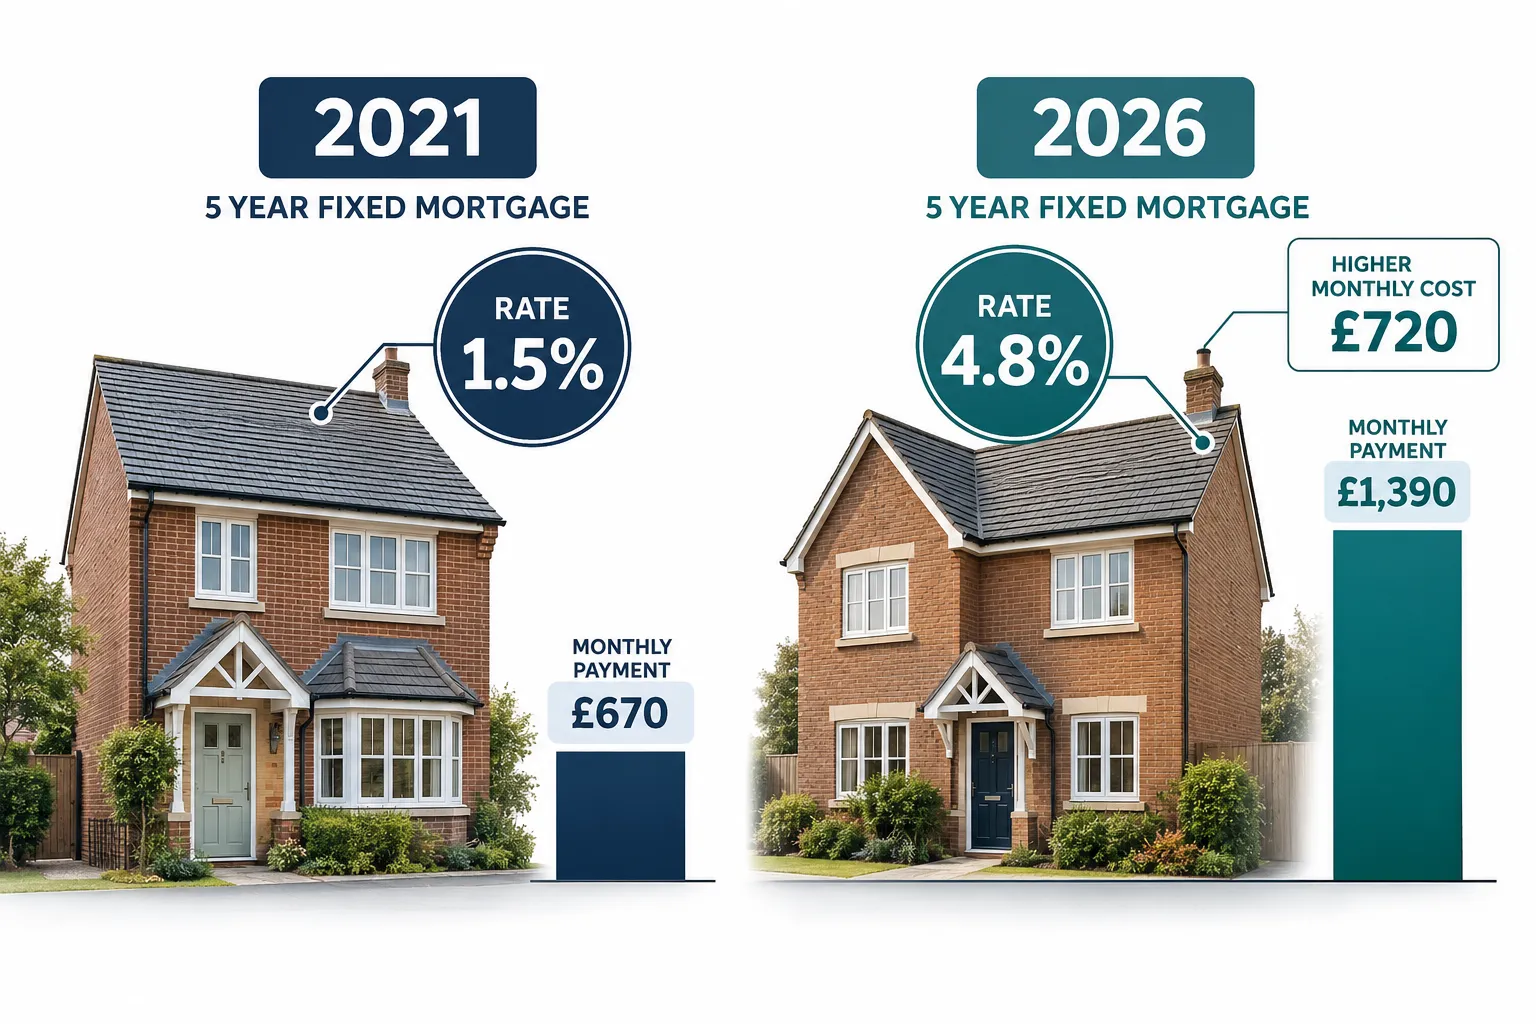
A homeowner who locked into a five-year fix back in November 2021 was paying roughly 1.30% interest. Five years on, the equivalent rate sits at 5.16%. That single number turns into an extra £4,884 a year on a typical £200,000 repayment mortgage, money that has to come from somewhere in an already stretched household budget.
This is not a hypothetical. It is the reality facing thousands of borrowers across the country this November, and many of them live within a short walk of Wimbledon station. If your five-year fixed remortgage Wimbledon deal is ending soon, the numbers deserve your full attention before the next Bank Rate decision lands.
Key Takeaways
- The average five-year fixed remortgage rate has jumped from 1.30% in 2021 to 5.16% today, adding about £407 a month, or £4,884 a year, on a £200,000 mortgage.
- First-time buyers on 95% loan-to-value two-year fixes face even steeper rises, with L&C estimating more than £3,900 a year in extra cost.
- More borrowers are researching tracker and variable deals, but trackers move directly with Bank Rate, currently 3.75%, so they carry real risk if rates rise further.
- Many lenders let you lock a new rate up to six months before your current deal ends, and some allow a switch to a cheaper rate before completion.
- A lender valuation sets your loan-to-value band and therefore your rate, so an independent RICS valuation can matter, especially if you have extended or improved the property.
Why the Five-Year Fixed Remortgage Wimbledon Market Has Shifted So Sharply
Back in late 2021, Bank Rate sat near historic lows and lenders competed fiercely for business with ultra-cheap fixed deals. That environment has gone. Bank Rate now stands at 3.75%, and CPI inflation was 3.5% in September according to the ONS, still above target, which keeps pressure on lenders' pricing.
David Hollingworth, associate director at L&C Mortgages, puts it plainly: "The sheer scale of the change in rates since late 2021 means that those coming to the end of a 5 year fixed rate will have to steel themselves for a big hike in mortgage rate."
The scale of the shift is clear when you line up the figures side by side.
| Mortgage type | 2021/earlier rate | 2026 rate | Extra cost per year |
|---|---|---|---|
| Five-year fixed remortgage | 1.30% (Nov 2021) | 5.16% | £4,884 |
| 95% LTV two-year fixed (first-time buyers) | 2.84% (2021) | 5.75% | over £3,900 |
| Two-year fixed remortgage | 3.89% (Aug 2025) | 5.13% | over £1,680 |
Even borrowers who fixed more recently are not immune. The two-year fixed remortgage rate has climbed from 3.89% in August 2025 to 5.13% now, adding more than £140 a month for many households.
Should You Gamble on a Tracker Instead of a Five-Year Fixed Remortgage Wimbledon Deal?
Faced with these numbers, a growing number of borrowers are tempted to look away from fixed rates altogether. Moneyfactscompare.co.uk reports that 24% of remortgage borrowers researched variable or tracker products in October, up from just 14% in February. Across all borrower groups, that share rose from 11% to 17%.
Adam French, head of consumer finance at Moneyfactscompare.co.uk, sums up the mood: "The figures suggest more borrowers are willing to gamble on interest rates to keep their initial mortgage costs down."
It is worth noting these figures measure online research, not completed applications, so plenty of browsing may not turn into borrowing. And trackers behave differently from fixed deals. As Hollingworth explains, "Unlike fixed rates, they react to base rate movement rather than expectation." A 0.25 percentage point rise, for example from 4.15% to 4.40%, would add roughly £28 a month to a tracker on a £200,000 mortgage over 25 years. The average new two-year tracker rate already rose from 4.54% to 4.68% during October alone.
For Wimbledon homeowners weighing a five-year fixed remortgage against a tracker, the real question is appetite for risk. A fix gives certainty for the whole term. A tracker could be cheaper if rates fall, but it could also rise again before your budget has room to absorb another increase.
Practical Steps Before Your Rate Resets
There are things you can do right now, regardless of which way rates move next.
- Start early. Many lenders allow you to secure a new fixed rate up to six months before your current deal ends, and some will let you switch to a cheaper rate if one appears before completion.
- Compare like for like. Look at total monthly cost, not just the headline rate, including any fees.
- Check your loan-to-value band carefully. Lenders set your rate based on their valuation of your home, and the band you fall into can make a meaningful difference to the rate on offer.
- Get independent advice. A mortgage broker can model both fixed and tracker scenarios against your own budget.
Where an RICS Valuation Fits Into Your Five-Year Fixed Remortgage Wimbledon Decision
This is the point many borrowers overlook. The lender's valuation determines which loan-to-value band you fall into, and that band drives the rate you are offered. A slightly lower valuation can push you into a worse band and cost you hundreds of pounds a year.
If your Wimbledon property has been extended, modernised, or improved since your last valuation, an automated or desktop valuation may not reflect that work. In those cases, an independent RICS valuation can provide solid evidence of current value to support your case with the lender, potentially unlocking a better rate band.
"A desktop valuation cannot see the extension you added two years ago, or the kitchen you rebuilt. An independent survey can put that evidence in front of the lender."
If you are weighing whether to improve your current home rather than move, it pays to check the condition of the building first. A professional survey can flag issues, damp, subsidence risk, roof condition, before you commit money to improvements that assume a sound structure underneath.
FAQ: Five-Year Fixed Remortgage Wimbledon Questions Answered
How much more will I pay coming off a five-year fix?
On a typical £200,000 repayment mortgage, the average five-year fixed rate has risen from 1.30% to 5.16%, adding about £407 a month, or £4,884 a year.
Is a tracker mortgage cheaper right now?
Not necessarily. Tracker rates move directly with Bank Rate, currently 3.75%. The average new two-year tracker rate rose from 4.54% to 4.68% in October alone, showing they can move against you quickly.
When should I start looking for a new deal?
Many lenders let you secure a new rate up to six months before your current deal ends, and some allow a switch if a cheaper rate appears before completion.
Why does my property valuation matter for remortgaging?
Your loan-to-value band, set by the lender's valuation, determines the rate you are offered. A higher valuation can move you into a cheaper band.
Should I get an independent RICS valuation?
If you have extended or improved your home, or if an automated valuation seems low, an independent RICS valuation can provide stronger evidence of value to support a better rate.
Is it better to improve my home or move?
That depends on your finances and the condition of the property. A survey before committing to major improvements can reveal structural issues that change the economics of staying put.
Conclusion
The jump from 1.30% to 5.16% on five-year fixed remortgages is not a minor adjustment, it is a near £5,000-a-year shock for many households approaching the end of their deal. Wimbledon homeowners facing this transition should act early, compare fixed and tracker options honestly, and pay close attention to how their property is valued. Book a rate up to six months ahead, ask about switching if rates improve, and if your home has changed since the last valuation, consider an independent RICS assessment before you accept the lender's first offer. A few weeks of preparation now could save thousands over the life of your next deal.
five-year fixed remortgage Wimbledon, remortgaging 2026, Bank Rate decision, mortgage rates UK, tracker mortgage risk, RICS valuation, Wimbledon property, mortgage advice, fixed rate mortgage, loan-to-value, L&C Mortgages, home improvement survey